Can I Use My Rolex for Liquidity While I Buy a Second Home in Montecito?
Yes. A Rolex may help you access short term liquidity while you arrange a purchase, renovation, or closing costs for a Montecito second home. Your main options are to sell it, borrow against it, or consign it for sale. Each route trades off speed, ownership, and potential proceeds differently.
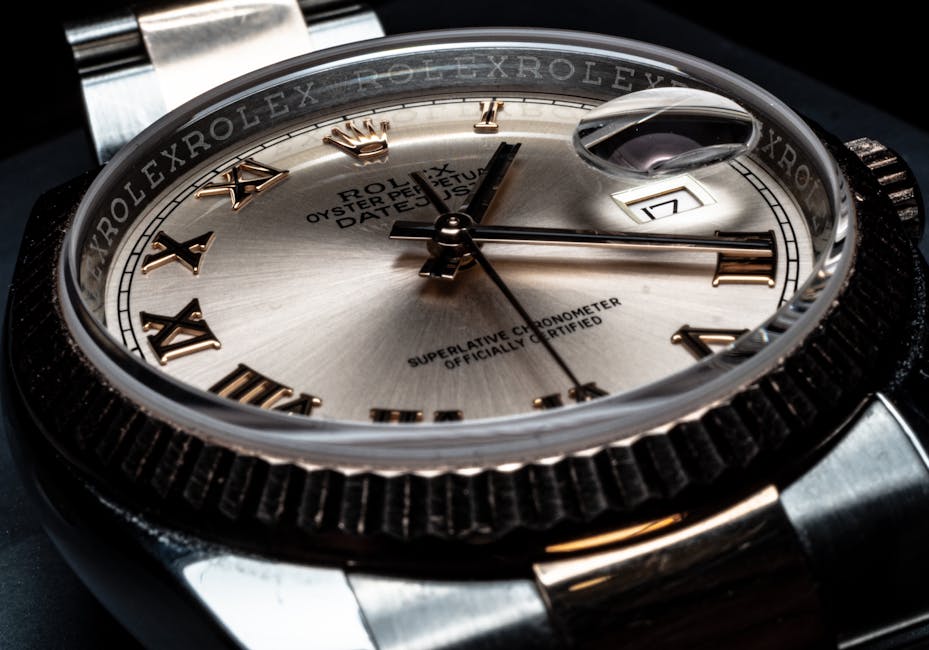
Before anyone talks numbers, I want to see the box and papers, if you have them. Then I want the reference, clear photographs, service history, and a close look at the watch itself. “A Submariner is a Submariner” is not a useful valuation method. Reference, condition, originality, and demand all matter.
The right choice depends on how much cash you need, when you need it, and whether keeping the watch matters to you. Here is how to compare the options without confusing a quick beverlyhillsmagazine offer with the best possible outcome.
Three Ways to Turn a Rolex Into Liquidity
Option Speed Do you keep ownership? Main trade-off Sell outright Often the fastest route, depending on the buyer and verification process No You receive a defined offer but give up the watch Borrow against the watch Can be relatively quick after appraisal and approval Usually, subject to the loan terms You take on repayment obligations and risk losing the watch if you default Consign Usually takes longer and depends on finding a buyer Until it sells, subject to the agreement You may achieve higher proceeds, but timing and final price are uncertainThese are different transactions, not three versions of the same offer. A sale ends your ownership. A watch collateral loan gives you funds while you retain an ownership interest, as defined by the agreement. Consignment puts the watch on the market through a seller or dealer, with payment typically following a completed sale.
Option 1: Sell Outright for Speed and Certainty
If the Montecito purchase has a firm deadline, selling outright may be the most straightforward choice. A dealer or buyer reviews the watch, confirms authenticity and condition, and makes an offer. If you accept, you can move toward payment without waiting for a retail buyer to appear.
The trade-off is that a quick sale often means accepting less than the price a patient seller might pursue through consignment. The buyer needs room to handle costs and risk, and may account for service, inventory time, and future resale. “Fast cash” usually means a discounted offer, not a special premium for urgency.
That does not make a direct sale a bad decision. Certainty has value when you need funds by a particular date, want to avoid managing a listing, or no longer wear the watch. Ask for a written offer that identifies the watch and the conditions attached to payment. Confirm how the buyer handles authentication, what happens if its inspection changes the offer, and when funds will arrive.
What to prepare before requesting an offer
- The reference and, if available, serial information. Share sensitive identifiers through a secure channel.
- Clear photographs of the dial, case, bracelet, clasp, and any visible wear.
- The box, papers, service records, and accessories, if you have them.
- An accurate account of repairs, polishing, replacement parts, or damage.
- Your deadline and the amount you need, so the buyer can tell you whether the transaction fits.
Complete documentation can help establish provenance and make evaluation more efficient, but missing papers do not automatically make a watch worthless. The buyer still needs to authenticate it and assess the actual example in front of them.
Option 2: Use a Watch Collateral Loan and Keep Ownership
A watch collateral loan may suit you if you need short term liquidity but expect to want your Rolex back. A lender evaluates the watch, sets loan terms, and holds the watch as collateral while you repay. The exact arrangement varies, so read the agreement rather than relying on a verbal summary.
Ask for the loan amount, interest rate, fees, repayment schedule, maturity date, and any extension or renewal rules in writing. Also ask where the watch will be stored, how the lender insures it, and what steps follow if you miss a payment or cannot repay on time. Understand when the lender may sell the collateral and whether you would owe any remaining balance under the contract and applicable law.
A loan amount will not necessarily match a watch’s retail replacement price or a seller’s expected asking price. Lenders consider how reliably they can authenticate and resell the watch, how quickly they might need to liquidate it, and the costs and risks they take on. A loan can preserve your ownership, but it is not free access to your watch’s full market value.
When borrowing may fit
- You want to keep the watch and have a credible repayment plan.
- You need funds before another source of money arrives.
- You understand the fees, deadline, and consequences of nonpayment.
- You have compared the loan cost with the cost of selling and replacing the watch later.
Do not borrow against a Rolex based only on a hoped-for future sale, bonus, or refinancing. Build a repayment plan around money you can reasonably expect, and consider what happens if that money arrives late. Pretty simple.. If the loan terms do not fit your timeline, selling may be the cleaner answer.
Option 3: Consign for Higher Potential Proceeds
Consignment can make sense when you can wait and want a specialist to present the watch to potential buyers. The consignor typically handles photography, listing, buyer questions, and transaction logistics. You receive proceeds after the watch sells and the agreed commission and costs come out.
Consignment may offer higher potential proceeds than a direct dealer purchase, but it does not guarantee a higher net result. The listing could take weeks or longer, the watch might not sell at the asking price, and market conditions can change while it sits. Consignment is not instant liquidity. If your closing date is fixed, do not count on an unsold watch as cash you can use that day.
Review the consignment agreement carefully. Confirm the asking price, minimum acceptable price, commission, insurance coverage, storage arrangements, listing period, and return process. Ask who can approve a discount and whether the consignor can accept an offer without your written approval. Clarify when the seller sends payment after a sale and what happens if a buyer returns the watch.
What Drives Rolex Value?
A defensible estimate starts with the specific watch, not a broad brand label. I look at three essentials: reference, condition, and originality. Then I compare the example with current market activity and account for the completeness of the set.
Reference
The reference identifies the model and configuration. Differences in metal, size, dial, bezel, bracelet, production period, and special features can affect buyer demand. Even watches within the same family can trade differently. A particular Submariner reference with a certain dial and bracelet is not interchangeable with every other Submariner.
Condition
Condition grading should describe what an evaluator can actually see and verify: case shape, scratches, dents, bracelet stretch, dial and hands, bezel, crystal, and mechanical performance. A polished case may look clean, but excessive polishing can soften edges and change the original profile. A watch that needs service may still be attractive, but the likely service cost can affect an offer.
Ask the evaluator to explain the grade and identify any assumptions. “Excellent” means little without a consistent standard or clear photographs. A reputable assessment should distinguish cosmetic wear from functional concerns and explain whether the watch has been tested.
Originality
Original components matter because collectors often want a watch that retains the parts and configuration appropriate to its reference. Replaced service parts, aftermarket components, refinishing, or a mismatched dial may change appeal. A replacement part does not automatically erase value, but the evaluator should identify it rather than gloss over it.

Box, papers, links, tags, and service records can support a more complete presentation. They do not override the watch’s condition or establish authenticity on their own. Authentication requires a proper examination of the watch and its details.
How to Get a Useful Estimate
For a realistic conversation, look for a dealer or specialist that combines authentication, consistent condition grading, and pricing from live secondary-market data. Live data helps show what comparable watches are doing now, rather than relying only on old auction results or optimistic asking prices. Still, market data is a reference point, not a guaranteed offer.
Ask what comparables the evaluator used and whether they reflect completed transactions or current listings. An asking price shows what a seller hopes to receive. A completed sale offers stronger evidence of what a buyer paid, though differences in condition, completeness, and timing still matter.
- Gather the watch, box, papers, service records, and extra links.
- Photograph the watch honestly in good light, including wear and damage.
- Request an assessment that names the reference and explains condition and originality.
- Compare the net proceeds and timing for sale, loan, and consignment.
- Read the written terms before handing over the watch or accepting funds.
For a high-value or unusual reference, consider a second independent opinion. Be wary of anyone who promises a precise number without examining the watch, or who pressures you to decide before explaining fees and terms.
Match the Choice to Your Montecito Timeline
Start with the cash need and the date you need it. If you have a near-term deadline and want certainty, request direct-sale offers and verify the payment timeline. If you want to retain the watch, compare watch collateral loan terms against a realistic repayment schedule. If you have flexibility and can wait for a buyer, consignment may be worth considering.
Do not treat the watch’s estimated value as a substitute for confirmed funds in a property transaction. A sale can require inspection, verification, and payment processing. A loan requires approval and a signed agreement. A consignment sale requires a buyer. Coordinate the watch transaction with your real estate, tax, and financial advisers, especially if the timing affects a deposit or closing.
The Bottom Line
Your Rolex can provide liquidity for a Montecito second home, but the best route depends on whether you value speed, continued ownership, or the possibility of higher proceeds most. Selling outright offers a cleaner path to a known payment once you accept the offer. One client recently told me was shocked by the final bill.. Borrowing against the watch can bridge a gap while you keep ownership, provided the repayment terms work. Consignment may improve your potential net proceeds, but it takes time and offers no guaranteed sale date.
Want to know something interesting? before you make a decision, have the watch authenticated, graded, and compared with relevant live secondary-market data. Bring the box and papers if you have them, disclose repairs or replaced parts, and get every offer or loan term in writing. That gives you a clearer view of what your Rolex can realistically do for your purchase, and what each option will cost you.